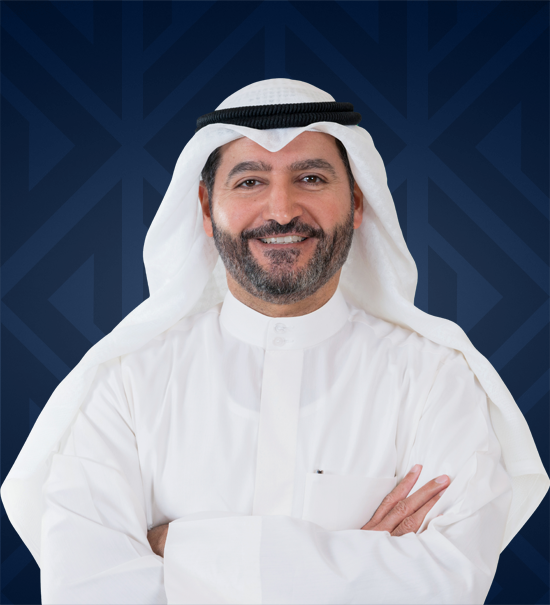

Hamad Abdulmohsen Al-Marzouq, Chairman of the Kuwait Banking Association and Chairman of Kuwait Finance House (KFH), affirmed that the Kuwaiti banking sector maintains strong financial positions, high levels of liquidity, and robust capital adequacy. This reflects the sector’s financial resilience and its capacity to navigate various economic and financial challenges, while continuing to play a pivotal role in financing economic activities and supporting development and financial stability in the State of Kuwait.
He noted that liquidity management within banks is based on the efficient allocation of financial resources, striking a balance between holding liquid assets and meeting financing requirements—all in accordance with prudential regulatory mandates and established risk management frameworks. He emphasized that assessing liquidity levels requires a comprehensive view of total liquid assets and the stability of funding sources, rather than focusing on any single line item on the balance sheet.
Financial Resilience Underpinned by a Prudent Regulatory Framework
Al-Marzouq highlighted that the Kuwaiti banking sector operates under a sophisticated regulatory framework overseen by the Central Bank of Kuwait. This framework is anchored in the application of international standards for financial soundness and risk management—including capital adequacy requirements, the Liquidity Coverage Ratio (LCR), and the Net Stable Funding Ratio (NSFR)—alongside rigorous stress testing and the continuous assessment of asset quality and the stability of funding sources. He explained that the strength of Kuwaiti banks’ financial positions is evidenced by liquidity levels and capital adequacy ratios that comfortably exceed regulatory requirements—a point previously highlighted by the Central Bank of Kuwait when it announced stimulus and prudential measures in March 2020.
He noted that these measures were part of a proactive regulatory policy aimed at enhancing the banking sector’s resilience and its capacity to navigate economic and regional developments, while ensuring the continued flow of financing to the national economy. He emphasized that temporary adjustments to certain regulatory requirements do not, in themselves, indicate any weakness in the banks’ financial positions; rather, they reflect the flexibility of prudential tools and their ability to adapt to varying economic conditions.
Al-Marzouq stressed that the robustness of the banking sector is not measured by fluctuations in specific financial balances, but rather by the soundness of banks’ financial positions, the quality of their assets, the adequacy of their capital, the stability of their funding sources, the efficiency of their liquidity and risk management, and their sustainable capacity to meet obligations and continue providing essential services and financing to the national economy.
Continued Capacity for Financing and Supporting Economic Growth
Regarding the banks’ ability to sustain their credit activities in the period ahead, Al-Marzouq affirmed that Kuwaiti banks possess the financial and operational flexibility required to manage their resources and regulatory obligations efficiently. He added that any future adjustments to prudential requirements would be implemented within the framework of established regulatory policies, with a focus on maintaining financial stability and the sustainability of banking operations. He added that the continued growth in credit and deposits—as indicated by the latest official data—reflects the banking sector’s capacity to sustain its role in financial intermediation, mobilizing savings, and channeling resources toward financing economic activities. This, in turn, supports economic growth and addresses the financing needs of individuals, corporations, and various productive sectors.
Confidence in the banking sector is anchored by robust financial and regulatory indicators
The Chairman of the Kuwait Banking Association concluded his statement by emphasizing that the Kuwaiti banking sector rests on a solid financial and regulatory foundation. The advanced levels achieved in capital adequacy, liquidity, and risk management reflect the success of the prudent regulatory approach adopted by the Central Bank of Kuwait, while strengthening the banks’ ability to navigate economic shifts and maintain financial stability.
He affirmed that Kuwaiti banks will continue to play a pivotal role in supporting the national economy and financing development projects and economic activities. This is underpinned by strong financial positions, prudent risk management, and a well-established regulatory framework—all of which reinforce the State of Kuwait’s standing as a highly reliable and stable financial and banking hub.